Home › Any driver courier vans · Updated
Any driver courier vansAny driver courier van insurance for shared vans
When staff, subcontractors or family take the wheel, the policy needs to cover every driver. Compare any driver and named driver courier van cover through specialist brokers.
Get started- Free to use
- No obligation to buy
- For shared vans and small courier fleets
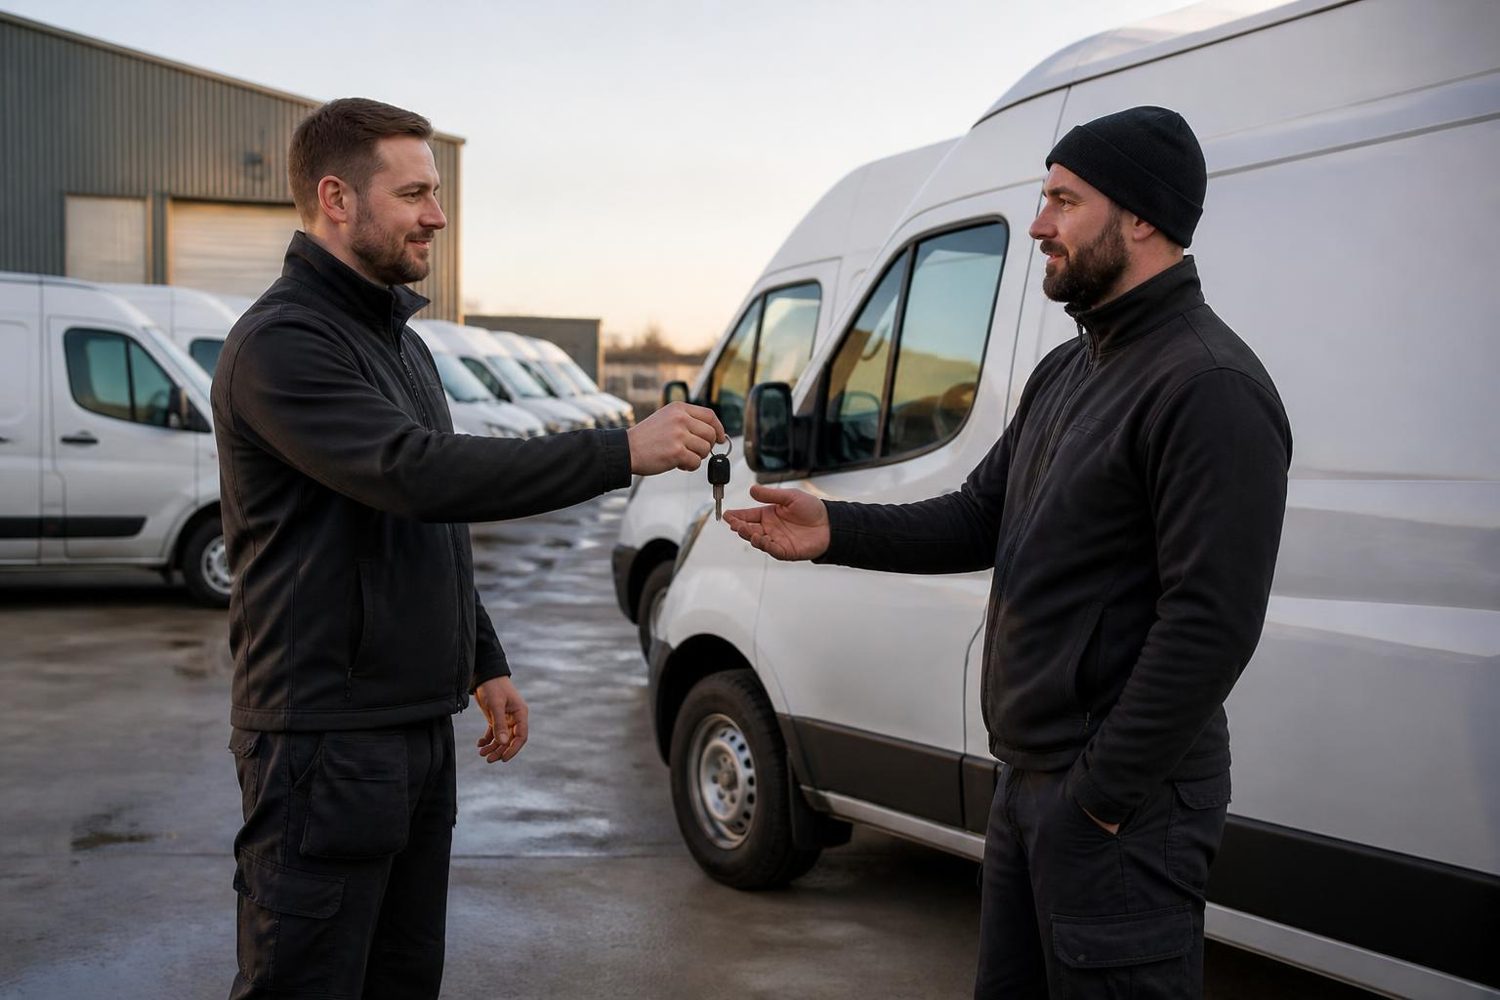
Any driver courier van insurance lets anyone who meets the insurer's conditions drive the van for hire and reward work, without each person being named on the policy. Those conditions usually include a minimum age and a minimum time holding a full licence, and sometimes a clean driving record. The alternative is a named driver policy, where only the people listed can drive.
- Specialist brokersCourier insurance brokers who arrange hire and reward cover every day.
- One short formTell us about the vehicle, the work and the drivers once.
- No obligationCompare the options you are offered and decide in your own time.
At a glance
- Any driver cover lets several people drive the van, as long as each one meets the policy conditions.
- Common conditions include a minimum age, a minimum licence-held period and limits on convictions.
- Named driver policies list each driver and can suit a small, stable team.
- Growing from one van to several may make a fleet policy worth asking about.
- Drivers who fall outside the conditions are not covered, even under an any driver policy.
- Key handovers and van sharing can affect theft and security conditions.
Named driver or any driver: who is actually covered
On a named driver policy, only the people listed on the certificate can drive the van. Each one is assessed on their own age, licence and history, and adding or removing someone usually means a change to the policy.
An any driver policy works the other way round. Instead of listing people, it sets conditions. Anyone who meets them, and has your permission, can drive. That flexibility suits businesses where drivers change often or cover each other's shifts.
When named driver cover can work
A sole trader with a partner who occasionally drives, or a small team that rarely changes, may find a named driver policy simpler and sometimes cheaper.
When any driver cover can work
Businesses using subcontractors, temporary staff or rotating drivers often find naming everyone impractical, and any driver cover removes the need to update the policy each time.
Age and licence conditions decide who can take the wheel
Any driver does not mean anyone at all. Insurers set rules, and a driver who falls outside them is uninsured on that van, whatever the policy is called.
Conditions insurers commonly set include:
- A minimum driver age, often higher for courier work than for private use
- A minimum period holding a full UK licence
- Limits on recent claims, convictions or penalty points
- Restrictions on certain licence types or provisional licences
- A requirement that drivers are employees, or that subcontractors are approved
Staff, subcontractors and family are treated differently
Some any driver policies cover only employees, and some extend to self-employed subcontractors. Others limit cover to the policyholder and family members. The difference matters if you hand a van to a subcontractor for a round.
It is also worth knowing whether the policy covers drivers using the van for personal reasons. A family member borrowing the courier van at the weekend may need social, domestic and pleasure use as well as meeting the driver conditions.
Growing from one van to a small courier fleet
Many courier businesses start with a single owner-driver and add vans as work grows. With two or three vans, separate policies are common. As the number rises, some insurers offer fleet or multi-vehicle policies that cover several vans under one renewal date.
Fleet policies are often written on an any driver basis with conditions for each driver. They can make admin simpler, but claims across all vans affect the whole policy. It is worth asking the broker at what point a fleet policy becomes an option for your business.
Growth also changes the other covers around the vans. More drivers can mean employers' liability becomes relevant, and more loads on the road at once can mean a higher overall goods in transit limit. These are worth raising at the same time as the van cover.
Questions worth asking before you buy any driver courier van insurance
These questions focus on who the policy covers and under what conditions.
- What is the minimum driver age?Younger staff or family members may fall outside the policy.
- How long do drivers need to have held a full licence?Newly qualified drivers are often excluded from any driver cover.
- Are subcontractors covered, or only employees?Handing a van to someone the policy does not include leaves them uninsured.
- What driving history is acceptable?Points, convictions or recent claims can rule a driver out.
- Is personal use covered for every driver?Some policies allow work use only for drivers other than the policyholder.
- Can more vans be added later?Knowing the route to multi-vehicle or fleet cover helps as the business grows.
- Are there key storage or security conditions?Shared vans can bring specific rules about keys and overnight parking.
Any driver courier van insurance questions
What does any driver mean on a courier van policy?
It means the policy covers anyone who meets its stated conditions and has your permission to drive. The conditions usually cover age, time holding a licence and driving history. Drivers who do not meet them are not covered.
Is any driver van insurance more expensive than named driver?
It often costs more because the insurer does not know exactly who will drive. For a business with changing drivers, it can still work out simpler than constantly updating a named driver policy. The difference depends on the conditions set.
Can a subcontractor drive my van on my insurance?
Only if the policy allows it. Some any driver policies cover employees only, while others include approved subcontractors. It is worth checking before handing over the keys.
Can a young driver go on an any driver courier policy?
Many any driver policies set a minimum age, so younger drivers may be excluded. Some insurers accept younger drivers on a named basis instead, often at a higher price. A broker can say which options exist.
What happens if a driver outside the conditions crashes my van?
That driver is likely to be treated as uninsured. The insurer may still deal with third party claims but can seek to recover the cost from you or the driver. Damage to your own van is unlikely to be paid.
When does a courier business need fleet insurance?
There is no fixed point, and insurers set their own thresholds for multi-vehicle and fleet policies. Many businesses look at it once they run several vans. It is worth asking a broker when the business starts to grow.
Ready to compare any driver courier van insurance?
One form, specialist brokers, no obligation.