Home › Car delivery drivers · Updated
Car delivery driversCompare car delivery driver insurance for side-income shifts
Picking up a few evening or weekend delivery shifts in your own car is a popular way to earn extra money. Courier Insure helps you find specialist brokers who can explain how to cover that work alongside your everyday car policy.
Get started- Free to use
- No obligation to buy
- For evening and weekend delivery shifts
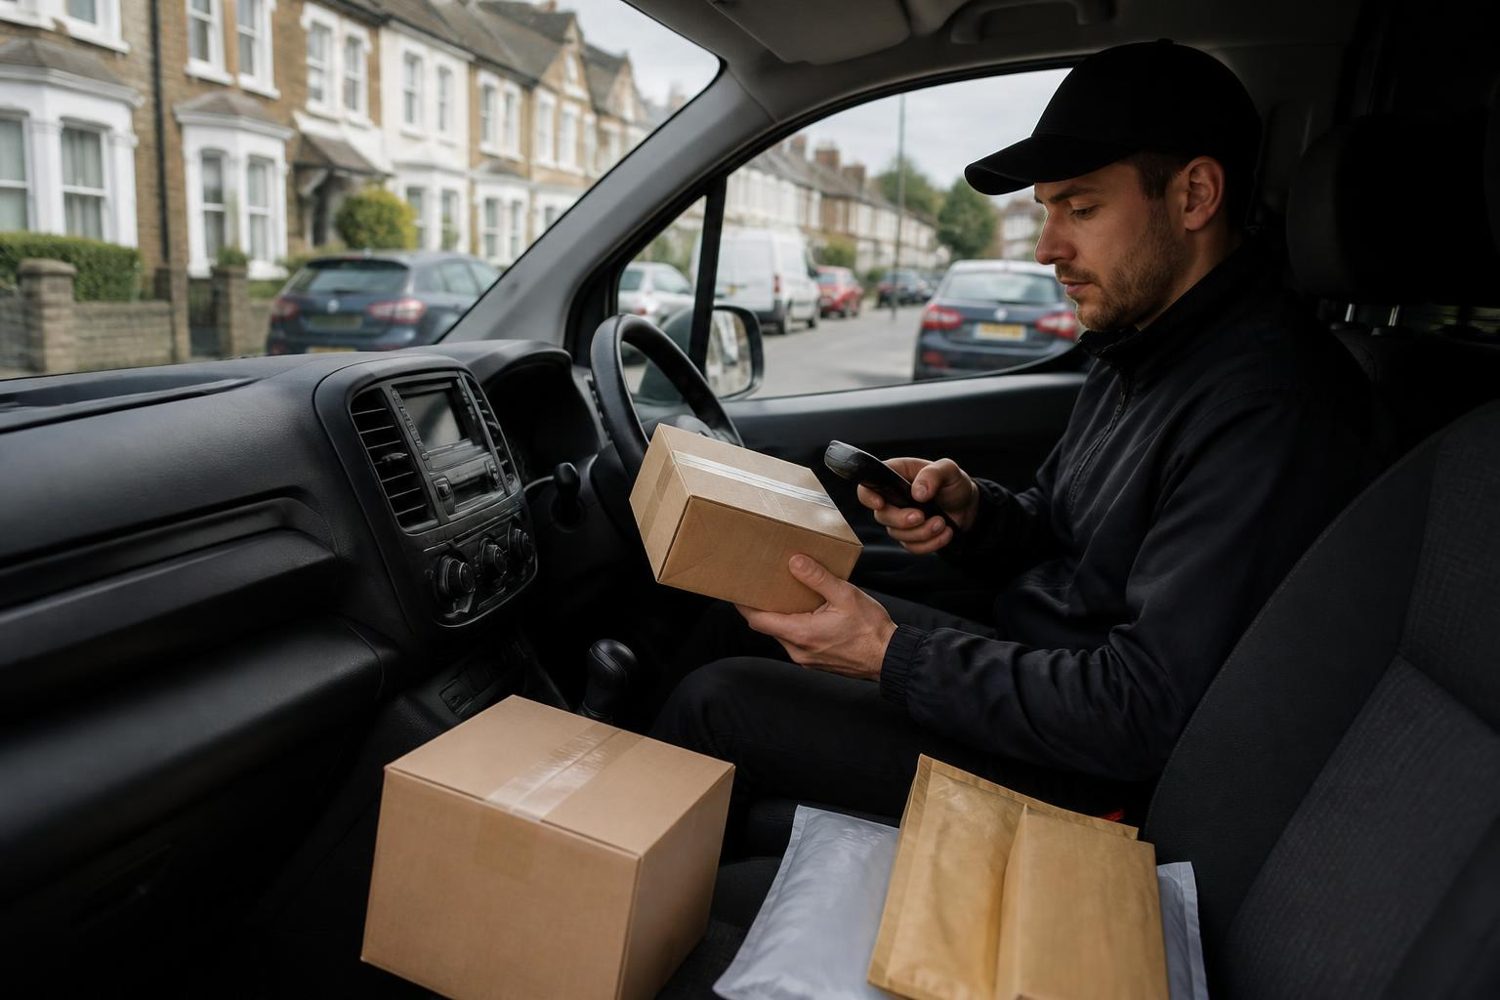
Car delivery driver insurance is cover for occasional or part-time paid deliveries in your own car, either added to your existing policy or arranged as separate courier cover. Your normal car policy almost certainly does not cover delivery work unless your insurer has agreed to it. The main choice is between extending the cover you already have or arranging a separate policy or top-up for the hours you deliver.
- Specialist brokersCourier insurance brokers who arrange hire and reward cover every day.
- One short formTell us about the vehicle, the work and the drivers once.
- No obligationCompare the options you are offered and decide in your own time.
At a glance
- Delivering for payment, even a few hours a week, is usually outside a standard car policy.
- Some insurers will add courier use to an existing policy and some will not.
- Separate or top-up cover can work alongside your personal policy for the hours you deliver.
- Telling your insurer before you start helps avoid a refused claim later.
- Driving without cover for delivery work can lead to points, a fine and difficulty getting insurance in future.
- Food and parcel deliveries are often treated differently, so the policy needs to match the work.
A few shifts a week still counts as delivery work
It is easy to think that occasional deliveries are too small to matter. Insurers generally do not see it that way. As soon as you carry goods or food for payment, the car is being used for hire and reward or courier work, regardless of how many hours you put in.
That applies whether you sign up to a delivery app, help a friend's business with drops on a Saturday, or take on seasonal work before Christmas. The question is not how often you deliver but whether the policy includes the type of use.
Extending your current policy or taking out separate cover
There are two broad routes for a part-time delivery driver. Which one fits depends on your insurer's appetite for courier work and how regularly you plan to deliver.
Adding courier use to your existing policy
Some insurers will add hire and reward or courier use for an extra premium, keeping everything on one policy. Others do not offer it at all, and the request may lead them to cancel or decline renewal, so it is worth asking before you start.
A separate courier policy
Specialist insurers offer car policies with courier use built in. This can suit drivers whose current insurer will not cover delivery work, or who plan to deliver regularly.
Top-up or hourly cover
Some products sit on top of your personal policy and are active only while you are working. These can suit irregular hours, but the level of cover usually depends on your main policy being in place.
Telling your insurer before your first delivery
Insurers expect you to tell them about anything that changes how the car is used. Starting delivery work is one of the biggest changes, and keeping quiet about it can cause problems even if you never make a claim.
When you contact your insurer or broker, it helps to have a few details ready so the conversation is quick and the answer is clear.
Information that usually helps:
- Whether you will deliver parcels, food or both
- Which app or company you plan to work for
- Roughly how many hours or shifts each week
- Whether anyone else will drive the car for deliveries
What can go wrong if delivery work goes undeclared
If you have an accident while delivering and the policy does not include that use, the insurer may refuse to pay for damage to your car. It may still have to pay third parties, but it can then try to recover that money from you.
The consequences can go beyond a single claim. Driving without cover for the way you use the vehicle can lead to points and a fine, and a cancelled policy or undisclosed use may need to be declared to future insurers, which can make cover harder to find.
- Claims for your own car may be refused
- You could be asked to repay costs paid to other people
- Points and a fine for driving without suitable cover
- Cancellation and a record that follows you to future quotes
Food or parcels: matching the policy to the shift
Many part-time drivers try both food and parcel delivery to see which pays better. Insurers often rate these separately, and some policies cover one but not the other.
If you switch between apps, it is worth checking that the policy names every type of delivery you plan to do. A policy that covers parcels may not cover a takeaway order, and the other way round.
Questions worth asking before you buy car delivery driver insurance
Part-time drivers often have an existing policy to work around, so these questions focus on fitting the two together.
- Will my current insurer add courier use, and on what terms?Some will, some will not, and the answer shapes everything else.
- If I use top-up cover, what happens if my main policy lapses?Most top-up products rely on a valid personal policy underneath.
- Does the cover include both food and parcels?Many policies cover only one type of delivery.
- Are there limits on the hours or days I can deliver?Some policies are built around occasional use only.
- Does the level of cover during deliveries match my personal policy?A comprehensive personal policy paired with third party delivery cover leaves a gap.
- Will adding courier use affect my no claims bonus?A claim during delivery work may affect the bonus on your main policy.
Car delivery driver insurance questions
Do I need to tell my insurer if I do delivery work on the side?
Yes, insurers expect to be told about changes in how the car is used. Delivery work is a significant change, and not declaring it could lead to a refused claim or a cancelled policy. It is worth contacting your insurer before your first shift.
Can I add delivery driving to my existing car insurance?
Some insurers will add courier or hire and reward use for an extra premium. Others do not offer it, in which case a separate courier policy or a top-up product may be the alternative. Asking your insurer directly is the quickest way to find out.
Is weekend delivery work covered by my normal car insurance?
Usually not. Standard car policies typically cover social, domestic and pleasure use and sometimes commuting or business use, but not carrying goods or food for payment. The number of shifts does not change this.
What happens if I crash while delivering on a normal car policy?
The insurer may refuse to pay for your car and may seek to recover any money paid to other people involved. You could also face points and a fine for driving without suitable cover, and future insurance may be harder to arrange.
Is hourly delivery insurance enough on its own?
Hourly or top-up cover is usually designed to sit on top of a personal car policy, not replace it. It is worth checking the terms to see what you need underneath and whether the level of cover matches.
Does car delivery driver insurance cover helping a friend's business?
If you are paid, even informally, to deliver goods that belong to someone else, it is usually treated as courier work. It is worth checking that the policy covers this type of use before you start.
Ready to compare car delivery driver insurance?
One form, specialist brokers, no obligation.